Harry's Bi-Weekly Update 10.22.26
October 22, 2026
HARRY’S BI-WEEKLY UPDATE
A Current Look at the Colorado Springs Residential real estate Market
As part of my “Special Brand of Customer Service”, it is my desire to share current Residential real estate issues that will help to make you a more successful and profitable Buyer and Seller.
TODAY’S RESIDENTIAL real estate MARKET IS CONTINUING TO BE A PUZZLE THAT’S NOT SO EASY TO SOLVE
There are still more questions than answers and quite honestly, today’s market is not one for the uninitiated or those who have to make quick decisions.
Existing homes for sale are increasing in number but days on the market are far longer than in recent times. In fact, even homes that were “priced right” are lowering prices more than once and some folks are even taking their homes off the market.
Outright price cuts are likely to become more common because the number of homes for sale is almost back to pre-pandemic levels. In September, inventory was just 5% below the same month of 2019 nationally, according to data from Realtor.com.
High mortgage interest rates are partly to blame as well as current economic conditions and political uncertainty.
It is most definitely a buyer’s market and for those who are looking, there are incentives available—from both sellers and lenders. In fact, in August, 45% of home sellers gave concessions to buyers, such as offering to cover the closing costs, paying for mortgage-rate buydowns or handing the buyer money for repairs.
Interesting to note, I’ve had some buyers who are “thrilled” they locked in 7% mortgages now that the rates are over 7.4%.
What we are seeing is that rates are “normalizing” and I just read that the average mortgage interest rate from 1982 through today is 7.7%.
You read that right! Some of you are still dreaming of the 3% rates of yesteryear but today there are more homes with mortgage rates at 5% or above than at 3%. What that tells us is that folks with the lower rates likely tired of waiting and moved on to other homes with mortgage loans at higher rates.
Young folks are getting help in the form of “family” down payment loans as well as having family co-signers. This is helping first-timers get into their own place and begin building home equity of their own.
Another interesting fact is the “housing market split”—homes at the top of the market—above $750,000-- are seeing sales climb by double digits, while those under that are showing much slower sales.
This chart illustrates that discrepancy:
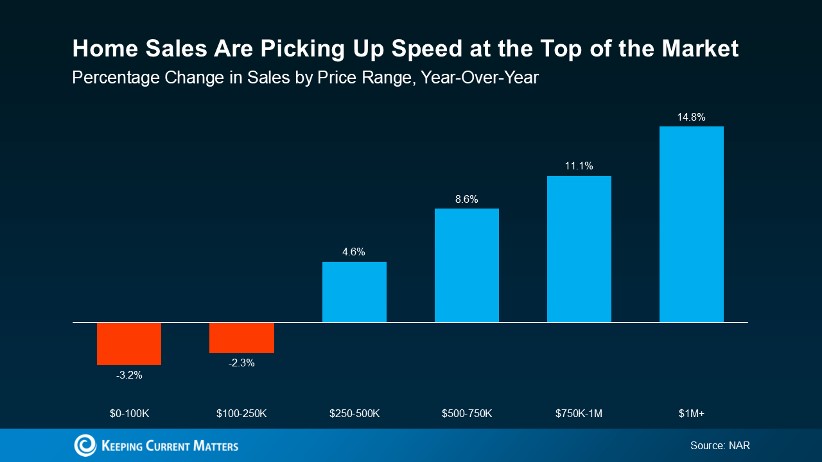
Luxury home buyers often pay cash or have a lot of equity in their current home to put down on the next one. These folks are less hampered by higher interest rates per se.
What does that mean if you are in the market but have been “on hold”?
Well, waiting is still going to cost you in the long run.
Yes, interest rates ARE higher than three or four years ago, or even last month, but they are likely to remain high for the near future.
However, home values are not going to remain as they are today based on what we have seen recently, as well as traditionally. They may not rise as quickly as they did three or four years ago, but they will continue to appreciate. Therefore, the longer you put off making a purchase, the more you will be paying for a new home.
New home construction has been hurt by interest rates as well and single-family housing starts fell in September to a 3 ½ year low, according to a report from the Commerce Dept this week.
Home builders are also offering various concessions to buyers if that is something you are considering for your next home. This is an area where I can help as well, and at no additional cost to you.
If you have been wanting to sell to trade up or move to a new neighborhood, you likely have more equity in your present home than you might imagine to use toward a down payment on a new home.
And as I mentioned earlier, another thing we’re seeing is that just because mortgage rates are listed at a certain price, there are many options to consider that could bring down the rate and thus lower your monthly payment.
One example is getting a 5-1 ARM (Adjustable-Rate Mortgage). Today’s rate is about one percentage point less that the average 30-year fixed-rate mortgage and the rate stays the same for the first five years. The idea is that if rates go down you will likely be able to refinance at a lower rate.
There are also buydown rates and various other options and I can help direct you to a lender who can explain all available choices so you can select the one the best fits your individual budget.
But you won’t know any of this until you give me a call.
I’ve been in the local Residential real estate arena for 53 years and that, along with my Investment Banking background, gives me a heads up in my ability to help my clients find not only the best home options for their wants, needs and budget requirements, but I can also help by directing them to lenders who have various options to fit their specific needs.
I provide my clients strategic solutions to whatever their Residential real estate needs and my expert negotiation skills go a long way to make certain they get the best deal possible, whether buying or selling.
So, yes, Residential real estate is a bit of a puzzle today but it’s one I can help you solve to meet your goals.
Give me a call at 719.593.1000 or email me at Harry@HarrySalzman.com and let me help you make your Residential real estate dreams come true.
HOME SALES RISE NATIONALLY FOR THE FIRST TIME SINCE MAY
The Wall Street Journal, 10.14.26
While it was a modest increase of 1.5% over the previous month, that seasonally adjusted increase nationally was good because economists had expected a decline of 0.8%.
Still, August and September marked the two slowest months for home sales this year, according to the National Association of Realtors (NAR). September sales were also down 2.2% year-over-year.
The “lock-in” effect where homeowners have held on to their low mortgage rates from years ago continued to ease as I mentioned earlier. September inventory nationally rose 1.9% from August, which is 4.6% higher than the previous year and the highest since 2019, NAR said.
So, a note to both buyers and sellers:
“Higher inventory and lengthening days on the market give buyers improved negotiating power,” said Lawrence Yun, NAR chief economist. “Home sellers need to be realistic about local market conditions, which could require price discounts and other incentives to attract buyers.”
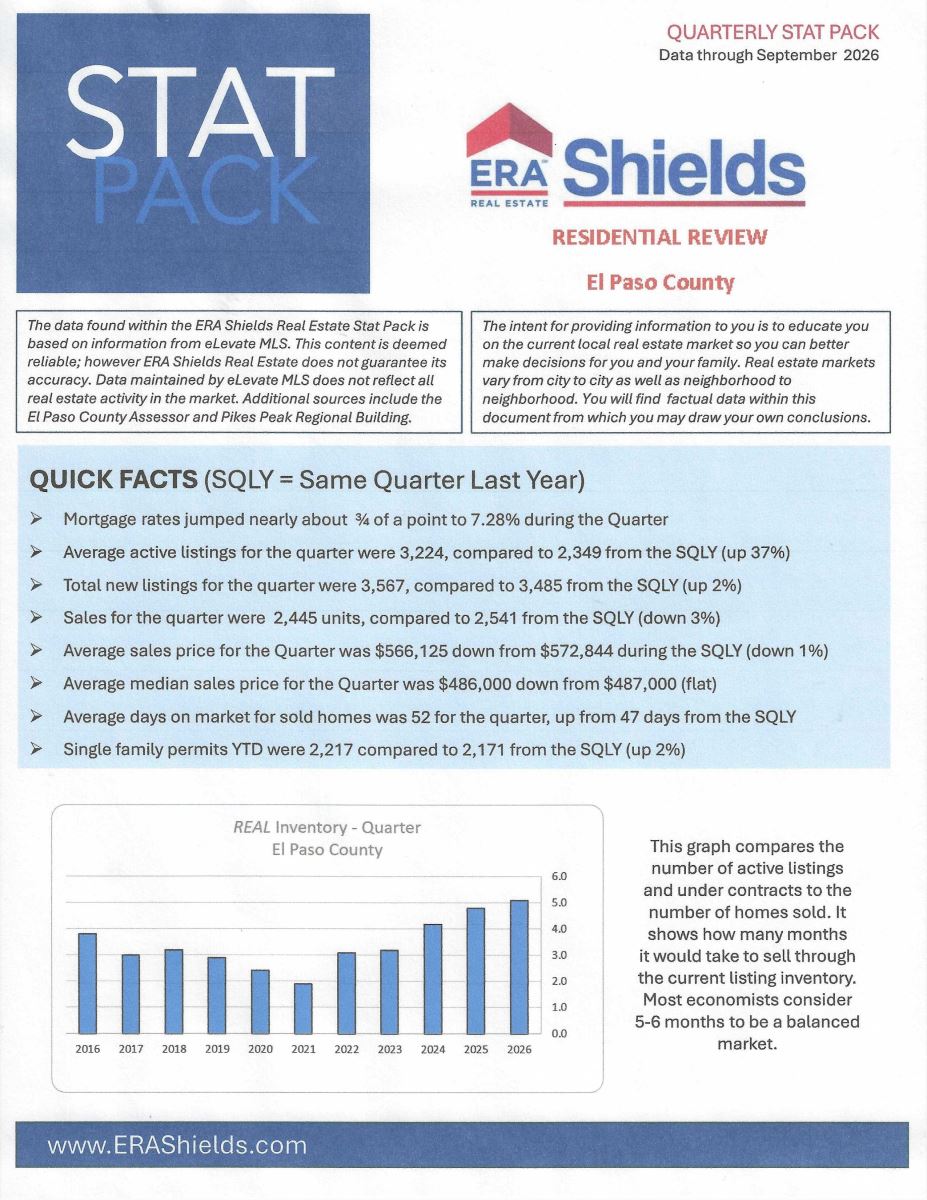
ERA SHIELDS QUARTERLY STAT PACK
Data through 3rd Quarter 2026, ERA Shields
Here is data from my company’s quarterly “Stat Pack” that can better help you understand the local buying and selling reality. I have reproduced the first page, and you can click here to get the 5-page report in its entirety.